Estate planning is becoming an increasingly important part of long-term financial preparation. In 2026, families are managing more diverse forms of wealth, including real estate, retirement savings, investments, business interests, and digital assets. At the same time, changing family structures and evolving financial priorities are encouraging individuals to take a more proactive approach to protecting what they have built.
Thoughtful estate planning strategies can help individuals organize their affairs, prepare for unexpected circumstances, and provide clearer direction for loved ones. Rather than treating estate planning as a one-time task, modern families are increasingly viewing it as an ongoing process that should evolve alongside their financial and personal circumstances.
The first step toward an organized estate plan is understanding what you own. A comprehensive inventory can include residential and commercial property, bank accounts, investment portfolios, retirement plans, insurance policies, business interests, valuable personal belongings, and digital assets.
For each major asset, keeping ownership information and relevant documentation in a secure location can make future administration considerably easier.
Financial inventories should not remain static. New investments, property purchases, inheritances, business transactions, and other significant changes can alter the overall financial picture.
Reviewing the inventory periodically helps ensure that important assets are not overlooked.
Modern wealth is increasingly diverse. A family may own traditional property alongside cryptocurrency, online businesses, intellectual property, websites, or digital investment accounts.
These newer forms of property can present challenges because they may require specialized access information or different methods of valuation and management.
Individuals should consider how each significant asset fits within their broader financial plan. A strategy that works well for a family home may not necessarily be appropriate for a privately held business or digital investment.
Taking a complete view of personal wealth can reveal planning gaps that might otherwise remain unnoticed.
Digital property deserves particular attention in today's estate planning process. Cryptocurrency, websites, online businesses, digital artwork, intellectual property, and electronic financial accounts may have substantial value.
However, family members may have difficulty locating or accessing these assets without proper documentation.
Creating a secure digital asset inventory can help identify important accounts and ownership information. Sensitive passwords and authentication details should be protected carefully rather than placed in an unsecured document.
Digital asset planning should also account for privacy and cybersecurity. Protecting financial information during a transition is just as important as making sure authorized individuals can eventually locate it.
Beneficiary designations are an important part of many financial accounts. Retirement plans and insurance policies, for example, commonly allow account holders to name individuals who should receive the proceeds.
These designations should be reviewed after major life events. Marriage, divorce, the birth of a child, or the death of a named beneficiary can all justify a review.
An outdated beneficiary designation may produce an outcome that no longer reflects someone's current intentions.
Keeping beneficiary information consistent with the overall financial plan can reduce confusion and help create a smoother transition for loved ones.
Estate planning is not only about what happens after death. Unexpected illness, injury, or incapacity can create immediate financial and personal challenges.
Individuals should consider how important decisions would be handled if they were temporarily or permanently unable to manage their affairs.
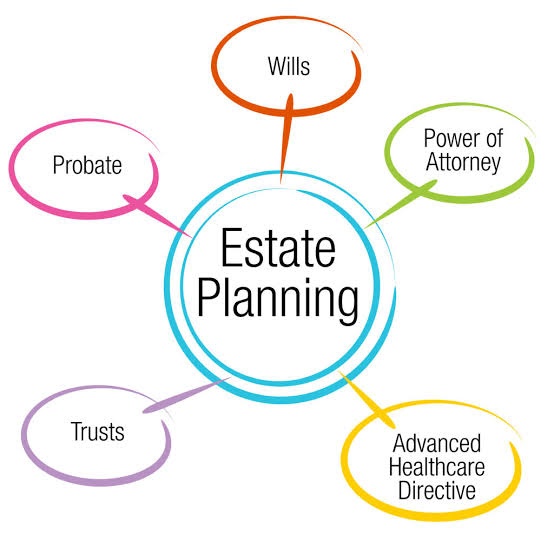
Appropriate legal documents can provide direction regarding financial management and other responsibilities, depending on individual circumstances and applicable law.
This preparation can be particularly important for business owners and people who manage significant investments. Planning ahead allows individuals to make decisions while they are able to clearly communicate their preferences.
Business owners have additional considerations when preparing for the future. A closely held company may represent a significant portion of a family's wealth, yet ownership and management can become uncertain without a succession plan.
A business succession strategy can address questions about future ownership, management responsibilities, potential successors, and the treatment of family members or business partners.
Starting these conversations early gives owners more time to evaluate different possibilities.
Succession planning can also help the next generation understand the responsibilities associated with managing a business rather than simply receiving an ownership interest without preparation.
Even a carefully designed estate plan can become difficult to use if important documents cannot be located.
Legal documents, property records, insurance policies, financial statements, tax information, business records, and account details should be stored securely and organized logically.
Digital backups can provide additional protection against physical loss, while trusted individuals should know where essential information is kept.
Good organization also makes periodic reviews easier. When documents are readily available, outdated information and missing records can be identified more quickly.
Estate planning involves more than documents and financial accounts. Communication can also play an important role.
Trusted family members may benefit from knowing where important records are located and understanding who may have future responsibilities. This does not require sharing every detail of an individual's finances.
Family conversations can also provide opportunities to discuss financial values, responsible investing, charitable giving, and long-term wealth preservation.
Clear communication can reduce misunderstandings and help future beneficiaries approach their responsibilities with greater confidence.
An estate plan should change when circumstances require it. Marriage, divorce, retirement, relocation, inheritance, business ownership, significant investments, or changes in family relationships may all justify a review.
Changes in applicable laws can also make periodic professional evaluation worthwhile.
One of the most practical estate planning strategies is therefore to establish a habit of reviewing the overall plan rather than waiting until a major problem appears.
Regular maintenance can help keep documents, beneficiary choices, asset ownership, and financial records aligned with current objectives.
Technology and financial innovation will continue influencing estate planning throughout 2026 and beyond. Digital investment platforms, secure cloud storage, automated financial tools, and new forms of digital ownership are changing how families manage wealth.
Despite these developments, the fundamentals remain straightforward: understand what you own, document your intentions, protect important information, and update your plan as circumstances change.
A flexible and organized approach can help families respond more confidently when unexpected events occur.
Estate planning is ultimately about preparation and control. It gives individuals an opportunity to make important decisions while they can clearly communicate their wishes and understand their financial circumstances.
By maintaining organized records, addressing digital assets, reviewing beneficiaries, preparing for incapacity, considering business succession, and communicating with trusted family members, individuals can create a stronger foundation for the future.
A thoughtful plan can provide greater clarity today while helping protect a family's financial legacy for generations to come.
This post has been authored and published by one of our premium contributors, who are experts in their fields. They bring high-quality, well-researched content that adds significant value to our platform.
Dutables provides reliable educational resources, study materials, academic guides, and learning content to help students and educators succeed.